A resource for understanding cr…
Credit Card Fraud Punishment: Legal Consequences
Understand the legal ramifications of credit card fraud and what penalties offenders may face.
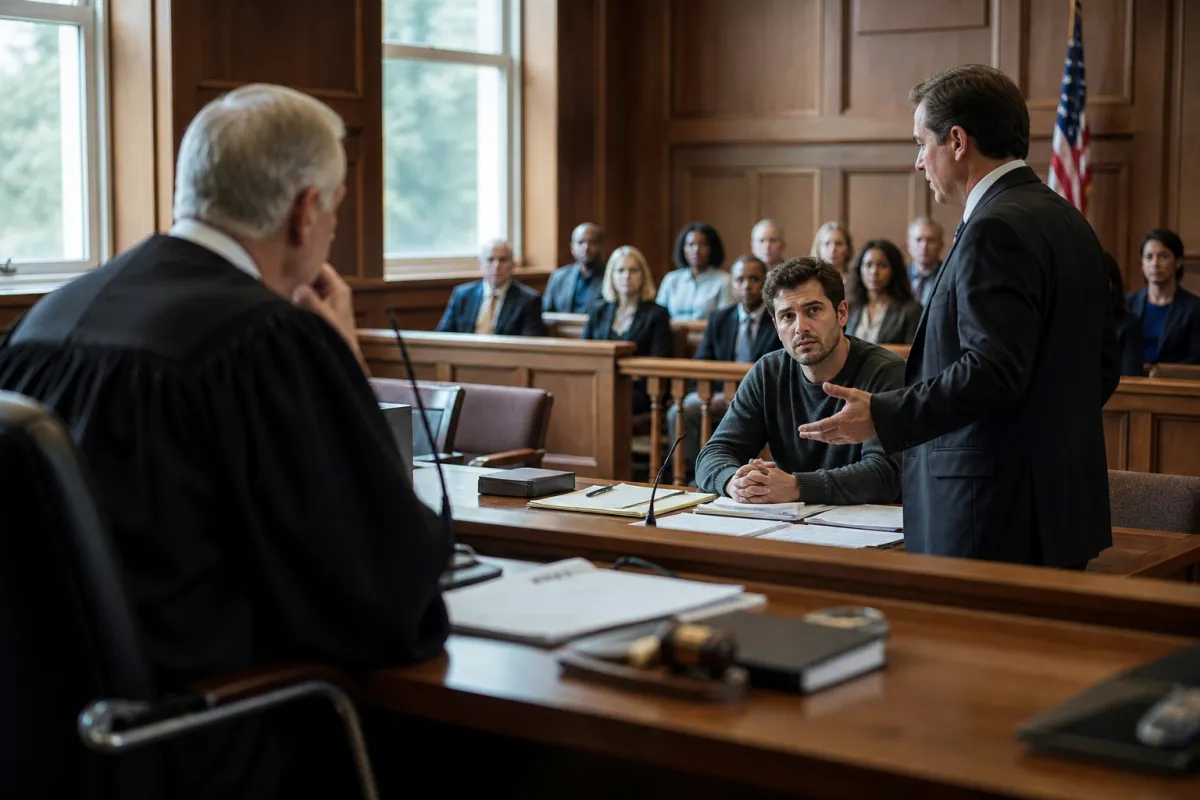
Exploring the legal consequences of credit card fraud in court.
Navigate
- Understanding Credit Card Fraud
- Legal Framework Surrounding Credit Card Fraud
- Penalties for Credit Card Fraud by State
- Factors Influencing Sentencing
- Consequences Beyond Imprisonment
- Common Defenses Against Credit Card Fraud Charges
- How Credit Card Fraud is Investigated
- Preventive Measures Against Credit Card Fraud
- Resources for Victims of Credit Card Fraud
- Credit Card Fraud Penalties by State
- Common Mistakes and Misconceptions
- Conclusions
- Links and references
Credit card fraud can result in significant legal consequences, including fines and imprisonment. Offenders using counterfeit or stolen cards to obtain $1,000 or more may face up to ten years in prison or fines of up to $10,000 (1). Average sentences for credit card fraud are approximately 28 months, with 95% of offenders receiving prison sentences (2). Penalties can vary based on the amount involved and the offender's history.
Understanding Credit Card Fraud
Credit card fraud refers to the unauthorized use of a credit card or its information to obtain goods, services, or funds. This crime can manifest in various forms, with skimming and phishing being among the most prevalent. Skimming involves the use of devices to capture card information during legitimate transactions, while phishing typically employs deceptive emails or websites to trick individuals into revealing their card details.
The impact of credit card fraud on victims can be severe, both financially and emotionally. In 2023, global fraud losses reached approximately $33.83 billion, with the United States accounting for $14.32 billion of this total (3). A significant proportion of fraud reports come from younger individuals, with those aged 20-29 representing 44% of reports filed in the same year (4). The average loss per fraud incident involving stolen payment cards was reported to be $79, with nearly 119 million stolen cards appearing on the internet (5).
Understanding the legal implications of credit card fraud is crucial for both potential offenders and victims. Federal laws impose severe penalties, including fines and imprisonment, with sentences varying based on the amount involved and the offender's prior record. For instance, credit card fraud involving amounts over $1,000 may lead to a prison sentence of one to five years, depending on the circumstances (6). Moreover, state laws further define the severity of penalties, such as in Florida, where credit card fraud is classified as a third-degree felony, punishable by up to five years in prison and fines up to $5,000 (7).
Victims of credit card fraud are encouraged to report incidents promptly to authorities and financial institutions, which can aid in the investigation and potentially lead to restitution. Preventive measures, including monitoring financial statements and using secure payment methods, can also mitigate risks associated with credit card fraud.
Legal Framework Surrounding Credit Card Fraud
The legal framework governing credit card fraud encompasses both federal and state laws, each with specific definitions and penalties. At the federal level, the primary legislation is found in Title 15 of the U.S. Code, which addresses fraudulent use of credit cards. Under 15 U.S. Code § 1644, individuals knowingly using counterfeit or stolen credit cards to obtain goods or services valued at $1,000 or more may face fines of up to $10,000 and imprisonment for up to ten years (1).
State laws also play a significant role in determining the legal consequences of credit card fraud. For instance, in Florida, credit card fraud is classified as a third-degree felony, punishable by a maximum of five years in prison and fines up to $5,000 (7). In Minnesota, if the value of property obtained exceeds $35,000, the offender may face up to 20 years in prison (8). These variations highlight the importance of understanding local laws, as penalties can differ significantly based on jurisdiction.
Key legal terms associated with credit card fraud include "aggravating circumstances" and "mitigating circumstances," which may influence sentencing outcomes. Aggravating circumstances, such as prior convictions or the involvement of organised crime, can lead to harsher penalties, while mitigating circumstances might reduce the severity of the sentence. The average sentence for credit card fraud offenders is approximately 28 months, with 95% receiving prison sentences (2).
Restitution is another important legal consideration, as courts may order offenders to repay victims for losses incurred due to fraud. The investigation process for credit card fraud typically involves collaboration between law enforcement, financial institutions, and victims to gather evidence and prosecute offenders effectively. Understanding these legal frameworks is crucial for both potential offenders and victims alike, as they navigate the complexities of credit card fraud and its consequences.
Penalties for Credit Card Fraud by State
The legal consequences for credit card fraud vary significantly across different states, influenced by the amount involved and the nature of the crime. In general, federal law stipulates that using a counterfeit or stolen credit card to obtain $1,000 or more can lead to a maximum penalty of ten years in prison and fines up to $10,000 (1). However, state laws often define penalties more specifically, with variations based on local statutes.
For example, in Florida, credit card fraud is typically classified as a third-degree felony, punishable by up to five years in prison and fines reaching $5,000 (7). If the fraudulent transaction is valued at less than $100, it may be charged as a first-degree misdemeanor, which carries lighter penalties (9). In contrast, Minnesota imposes more severe penalties; if the fraud involves property valued over $35,000, offenders may face up to 20 years in prison (8).
In Wyoming, recent legislation has made the unlawful use of a credit card subject to imprisonment and fines, although specific penalties were not detailed in the latest updates (10). The sentencing guidelines in various states also consider aggravating and mitigating circumstances, which can affect the length of imprisonment and the amount of fines imposed. For instance, repeat offenders may face harsher penalties, while first-time offenders might receive lighter sentences, particularly if mitigating factors are present (11).
Nationwide, the average sentence for credit card fraud is approximately 28 months, with 95% of offenders receiving prison sentences (2). This statistic underscores the seriousness with which credit card fraud is treated across jurisdictions. Understanding these differences is crucial for both potential offenders and those interested in fraud prevention, as penalties can significantly impact the consequences of credit card fraud.
Factors Influencing Sentencing
Sentencing for credit card fraud is influenced by various factors, including the amount involved, the offender's prior criminal history, and the intent behind the fraud. Generally, the greater the financial loss, the more severe the penalties. For instance, credit card fraud involving amounts over $1,000 can lead to prison sentences ranging from one to five years, depending on the specific circumstances of the crime (6). In contrast, smaller fraudulent transactions may result in lesser penalties or misdemeanour charges.
Prior offenses play a significant role in determining the severity of the sentence. Repeat offenders often face harsher penalties compared to first-time offenders. According to federal laws, penalties increase for those with a history of credit card fraud or related crimes, reflecting the legal system's approach to deterring habitual offenders (11). For example, an individual with previous convictions may receive a longer sentence than someone committing fraud for the first time, even if the amounts involved are similar.
Intent is another critical factor in sentencing. Courts may consider whether the offender acted with malicious intent or if the crime was committed under duress or due to a misunderstanding. Mitigating circumstances, such as mental health issues or the absence of prior criminal behaviour, can lead to reduced sentences (2). Conversely, aggravating circumstances, such as the involvement of organised crime or significant financial losses to victims, can result in more severe penalties. For example, if the total amount involved in the fraud exceeds $35,000, as seen in Minnesota, offenders may face up to 20 years in prison (8).
Overall, the complexities of sentencing in credit card fraud cases highlight the importance of understanding both state and federal laws, as well as the specific circumstances surrounding each case. Victims of fraud are encouraged to report incidents promptly, as this can aid in the legal process and potentially influence sentencing outcomes.
Consequences Beyond Imprisonment
The legal consequences of credit card fraud extend beyond imprisonment, encompassing fines, restitution, and long-term impacts on an individual's financial and professional life. Offenders convicted of credit card fraud may face significant fines, which can reach up to $10,000 for serious offences involving substantial amounts, such as $1,000 or more (1). In some states, like Florida, fines can be as high as $5,000 for third-degree felonies related to credit card fraud (7). These financial penalties serve as both punishment and deterrent, reflecting the seriousness with which the legal system views such crimes.
Restitution is another critical aspect of the penalties associated with credit card fraud. Courts often require offenders to repay victims for the losses incurred due to their fraudulent actions. This obligation can significantly affect the offender's financial situation, especially if the restitution amount is substantial. The restitution process typically involves a thorough investigation of the losses suffered by victims, and courts may consider various factors when determining the amount to be repaid.
Beyond immediate financial penalties, credit card fraud can have long-term repercussions on an individual's credit score and employment opportunities. A felony conviction can severely damage one's credit rating, making it challenging to secure loans, rent properties, or obtain credit cards in the future. Individuals with a history of credit card fraud may also encounter difficulties in the job market, as many employers conduct background checks and may view such convictions unfavourably. This is particularly true in industries that require financial trustworthiness, such as banking and finance.
The ramifications of credit card fraud are not limited to the offender alone; they also extend to the broader financial system. In 2023, card issuers and merchants faced losses totalling approximately $33.83 billion due to fraud, with the U.S. accounting for $14.32 billion of that total (3). Such staggering figures highlight the widespread impact of credit card fraud, underscoring the importance of preventive measures and legal consequences aimed at reducing these crimes. Understanding these additional consequences is crucial for both potential offenders contemplating their actions and individuals seeking to understand the far-reaching effects of credit card fraud.
Common Defenses Against Credit Card Fraud Charges
Defending against credit card fraud charges can involve various strategies, with the effectiveness of each dependent on the specific circumstances of the case. A common defense is the lack of intent. For instance, if an individual mistakenly used a credit card that they believed was valid, this could potentially negate the intent required for a fraud conviction. Demonstrating that the defendant had no knowledge of the card being counterfeit or stolen can be crucial in such cases.
Another viable defense is mistaken identity. If the accused can provide evidence that they were not present at the time of the alleged fraud or that they were misidentified, this can lead to a dismissal of charges. For example, if a credit card was used in a different state while the accused can prove they were elsewhere, this can work in their favour.
Additionally, the defense may argue the violation of rights during the investigation process. If law enforcement conducted an unlawful search or seizure, any evidence obtained could be deemed inadmissible in court, potentially resulting in the charges being dropped. Courts take the constitutional rights of individuals seriously, and any breach can significantly impact the prosecution's case.
Successful defenses have been observed in cases where defendants provided credible alibis or demonstrated a lack of prior criminal behaviour. For instance, individuals with clean records who can show they were victims of credit card skimming or phishing schemes might receive more leniency. This highlights the importance of gathering evidence and presenting a strong case to counter the charges effectively.
Ultimately, the strategy employed will depend on the specifics of the case, including the nature of the alleged fraud and the evidence available. Understanding these defenses can help individuals navigate the complexities of credit card fraud charges and the legal consequences that may follow.
How Credit Card Fraud is Investigated
The investigation of credit card fraud is a multifaceted process involving law enforcement, financial institutions, and victims. Initially, when a fraudulent transaction is reported, banks and credit card companies initiate an internal investigation to identify any unusual activity on the account. This process often includes reviewing transaction histories, monitoring for patterns that indicate fraud, and employing advanced technology such as artificial intelligence to detect anomalies in spending behaviour. For instance, machine learning algorithms can flag transactions that deviate from a user's typical spending patterns, prompting further investigation.
Once a preliminary assessment indicates potential fraud, financial institutions typically collaborate with law enforcement agencies. Investigators may gather evidence such as surveillance footage, transaction records, and customer statements. In cases involving large-scale fraud or organised crime, federal agencies like the Secret Service may become involved, especially when the financial losses exceed $1,000, which can lead to significant legal consequences, including fines and imprisonment (1). In 2023, the total fraud losses reached $33.83 billion globally, evidencing the scale of the problem and the necessity for thorough investigations (3).
Technology also plays a critical role in the investigation process. Tools such as transaction monitoring systems and fraud detection software are routinely used to identify suspicious activities. These systems can analyse vast amounts of data in real-time, allowing for swift action to mitigate potential losses. Moreover, data analytics can help trace the origins of fraudulent transactions, aiding in the identification of methods like skimming or phishing that offenders may employ.
Victims of credit card fraud are encouraged to report incidents promptly, as this facilitates a more effective investigation. Timely reporting can lead to quicker recovery of stolen funds and may assist in the apprehension of offenders. It is crucial for individuals to understand their rights and the resources available to them, as well as to take preventive measures to protect their financial information from potential fraud.
Preventive Measures Against Credit Card Fraud
Preventing credit card fraud requires a combination of individual vigilance and effective business practices. Individuals can take several proactive steps to safeguard their financial information. Regularly monitoring bank statements and credit card activity is essential; studies indicate that prompt detection of unauthorized transactions can significantly reduce potential losses. For example, 30% of fraud cases are resolved when reported within 30 days (4).
Utilising strong, unique passwords for online accounts and enabling two-factor authentication (2FA) can further enhance security. According to cybersecurity experts, accounts with 2FA are 99% less likely to be compromised than those without (12). Additionally, being cautious while shopping online, such as ensuring that websites are secure (indicated by "https://" in the URL), can help avoid phishing scams.
Businesses also play a critical role in preventing credit card fraud. Implementing advanced fraud detection systems can identify suspicious transactions more effectively. In 2023, external fraud was reported as the primary operational risk for financial institutions, highlighting the need for robust protective measures (12). Training employees to recognize signs of fraud, such as unusual purchasing patterns or customer behaviours, is vital.
Moreover, businesses should consider adopting EMV chip technology, which has been shown to reduce counterfeit fraud by 76% since its implementation in the United States (11). For businesses accepting card payments, maintaining compliance with Payment Card Industry Data Security Standards (PCI DSS) is essential to protect cardholder information.
In summary, a comprehensive approach encompassing personal vigilance and robust business practices is critical in mitigating the risk of credit card fraud. By actively engaging in preventive measures, both individuals and businesses can contribute to a safer financial environment, reducing the overall incidence of fraud and its associated costs.
Resources for Victims of Credit Card Fraud
Victims of credit card fraud have access to various resources designed to provide support and assistance throughout the recovery process. Reporting the fraud promptly is crucial, as it can help in recovering lost funds and preventing further unauthorized transactions. Victims are encouraged to contact their credit card issuer immediately to report the fraudulent activity, as many companies have dedicated fraud hotlines specifically for this purpose.
In addition to contacting financial institutions, victims can benefit from legal assistance. Numerous organisations offer free or low-cost legal services to individuals facing difficulties due to credit card fraud. For example, the Legal Services Corporation provides information on finding legal aid near you, which may include assistance with understanding rights and pursuing restitution (6).
Support groups and hotlines also play a vital role in helping victims cope with the emotional and financial stress associated with fraud. The Federal Trade Commission (FTC) operates the Identity Theft Hotline, which can be reached at 1-877-IDTHEFT (1-877-438-4338). This hotline offers guidance on steps to take after identity theft, including credit monitoring and fraud alerts. Furthermore, local consumer protection agencies may provide additional resources tailored to specific state laws and regulations regarding fraud (7).
Victims should also consider contacting credit bureaus to place a fraud alert on their credit reports. This alert signals to potential creditors that the individual may be a victim of fraud, making it more difficult for fraudsters to open new accounts in their name. Each of the three major credit bureaus—Experian, TransUnion, and Equifax—offers this service.
Ultimately, victims of credit card fraud should be proactive in utilising available resources to navigate the recovery process effectively. Engaging with hotlines, legal assistance, and consumer protection agencies can provide crucial support in addressing the challenges that arise from such incidents.
Credit Card Fraud Penalties by State
- State
- Florida
- Classification
- Third-degree felony
- Prison Time
- Up to 5 years
- Fines
- Up to $5,000
- State
- Minnesota
- Classification
- Felony (over $35,000)
- Prison Time
- Up to 20 years
- Fines
- Depends on case
- State
- Wyoming
- Classification
- Unlawful use
- Prison Time
- Depends on circumstances
- Fines
- Depends on circumstances
- State
- General (U.S.)
- Classification
- Felony (over $1,000)
- Prison Time
- 1 to 5 years
- Fines
- Up to $10,000
Common Mistakes and Misconceptions
Believing Credit Card Fraud is a Minor Offence
Many individuals perceive credit card fraud as a minor crime, often underestimating its legal consequences. This misconception can lead to a lack of caution when engaging in suspicious activities. In reality, credit card fraud involving amounts over $1,000 can result in prison sentences ranging from one to five years, depending on the circumstances of the crime (6). Understanding the severity of these penalties is crucial for individuals contemplating their actions.
Assuming All States Have the Same Penalties
A common error is the assumption that penalties for credit card fraud are uniform across the United States. This belief can result in individuals being unprepared for the specific legal repercussions they may face in their state. For instance, in Florida, credit card fraud is classified as a third-degree felony, punishable by up to five years in prison and fines up to $5,000 (7). Awareness of state-specific laws is essential for understanding potential consequences.
Overlooking Long-Term Consequences Beyond Imprisonment
Many individuals focus solely on the immediate risk of imprisonment when considering credit card fraud, neglecting the long-term implications. Such consequences may include lasting damage to one’s credit score, difficulties in obtaining loans, and potential civil lawsuits from affected parties. Engaging in credit card fraud can lead to financial instability and a tarnished reputation, which can affect personal and professional opportunities for years to come.
Underestimating the Effectiveness of Legal Defences
Some individuals mistakenly believe that they have no viable legal defences against credit card fraud charges. This misconception can discourage them from seeking legal assistance. In reality, common defences such as lack of intent or mistaken identity can be effective in court, depending on the specifics of the case. A well-prepared defence strategy can significantly alter the outcome of fraud charges, highlighting the importance of legal representation.
Ignoring the Scale of Fraud and Its Impact
Individuals often underestimate the scale of credit card fraud and its implications for the financial system. In 2023, fraud losses incurred by card issuers and merchants reached $33.83 billion worldwide, with U.S. losses amounting to $14.32 billion (3). This substantial financial impact underscores the seriousness of credit card fraud and the necessity for robust preventive measures. Recognising the broader context can foster a greater sense of responsibility among individuals regarding their financial activities.
Conclusions
Credit card fraud is a serious offence, with penalties including prison sentences of 1 to 20 years, depending on the amount involved and state laws.
Misconceptions about the severity of credit card fraud can lead to unintentional engagement in risky behaviours, which may have long-lasting legal and financial consequences.
Awareness of state-specific penalties is crucial, as they can vary significantly; for example, Florida imposes up to five years of imprisonment for third-degree felonies.
Proactive measures, such as regular monitoring of financial accounts and understanding legal rights, can mitigate the risks associated with credit card fraud.
Legal defences exist, and individuals facing charges should seek professional legal assistance to explore their options.
For further information on potential prison time related to credit card fraud, refer to Credit Card Fraud Jail Time: What You Need to Know.
Explore More on Fraud Prevention
Discover additional resources to enhance your understanding.
View More ArticlesRead next
 Clone Credit Card: How It Happens and Prevention TipsLearn how clone credit cards are created and discover effective prevention tips to protect your finances from fraud.
 ATM Skimmer Pilot Travel Center: A GuideDiscover how to protect yourself from ATM skimmers at Pilot Travel Centers, ensuring secure transactions while on the road.
 Credit card skimmer detectorDiscover effective credit card skimmer detectors to protect your finances from fraud. Learn how to choose the right tool for your needs.